If you’re considering selling your life insurance policy, Coventry Direct is probably one of the companies you’ve encountered during your research.
Coventry is a well established name in the life settlement industry, as they are the largest of all the buyers, and many seniors inquire with them when considering selling their life insurance policy.
The first thing seniors want to know is how much Coventry might pay for their existing coverage. That answer depends on several factors, including your age, health, policy type, death benefit, and future insurance premiums.
But there is something equally important to understand.
The amount Coventry Direct offers for your life insurance policy is not necessarily the highest amount another institutional buyer would be willing to pay.
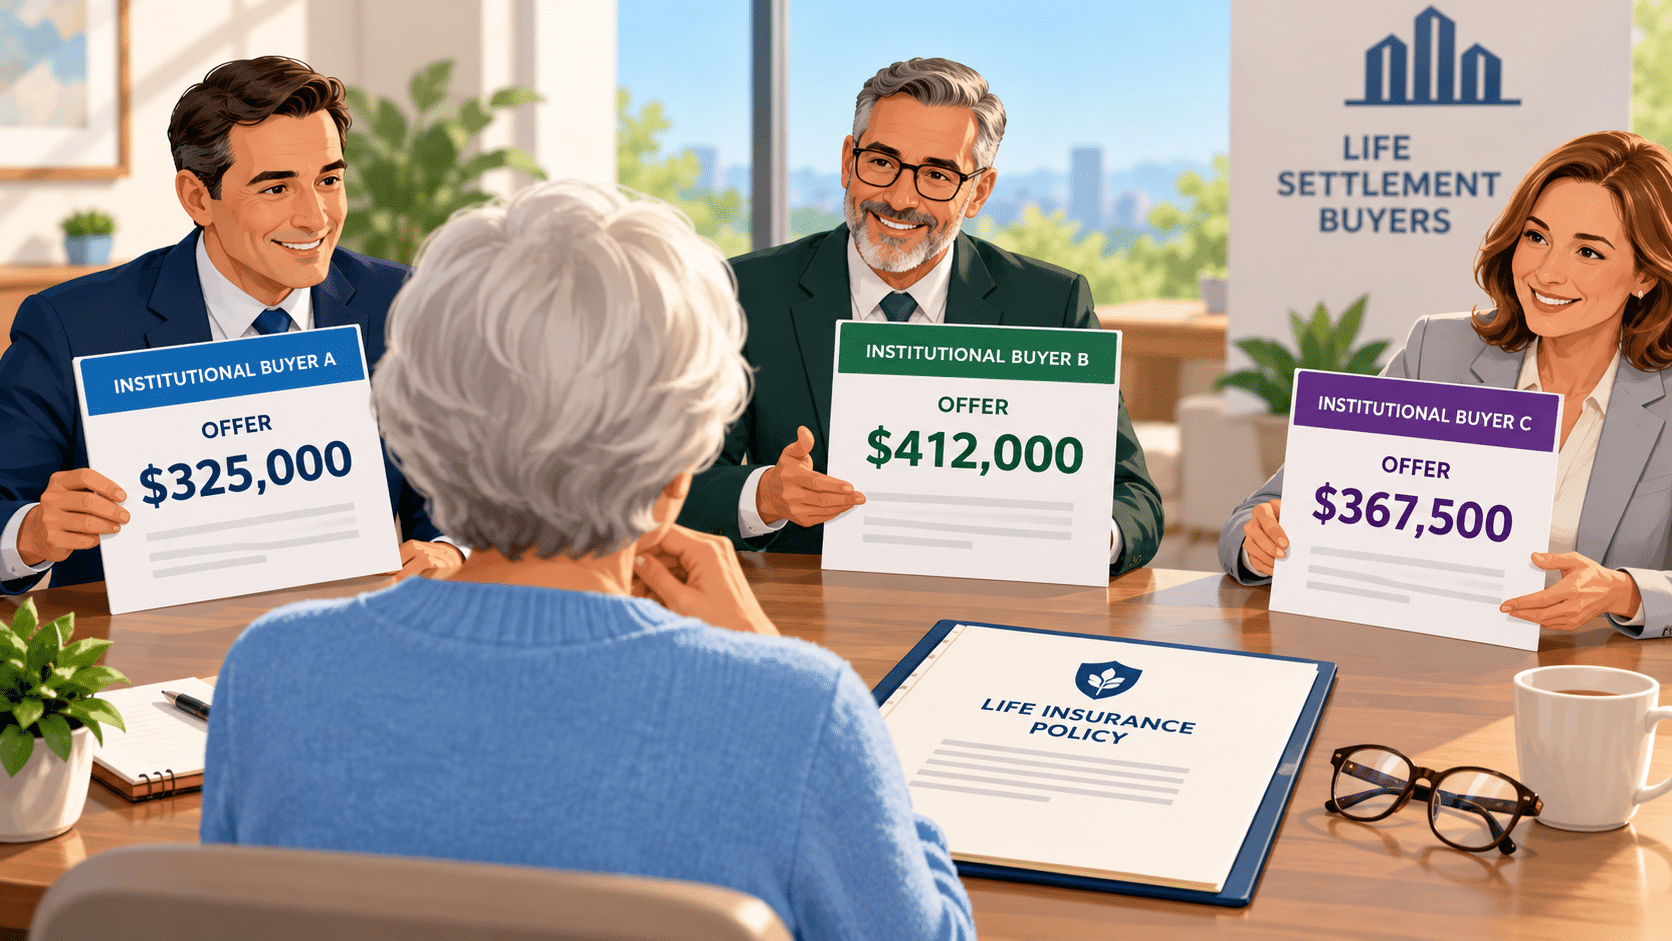
Life settlements are negotiated transactions, and different buyers can place substantially different values on the same policy.
Understanding how these offers are determined can help you make a more informed and savvy decision before selling.
How Coventry Direct Determines What Your Policy Is Worth
Coventry Direct is an institutional buyer in the life settlement market. They purchase life insurance policies directly from policyholders, a transaction known as a life settlement.
A life settlement allows an eligible policyholder to sell an existing life insurance policy to a third party, such as Coventry Direct, for a lump-sum payment. The purchaser assumes responsibility for future premiums and ultimately receives the death benefit.
The value of a policy depends primarily on the financial obligations and expected returns associated with maintaining the coverage.
Several factors influence the amount an institutional buyer may offer.
Age and health: Institutional buyers generally favor older insured individuals, particularly those age 75 and above. Serious health conditions can also influence eligibility and valuation.
Death benefit: Larger policies often attract greater institutional interest. Policies with death benefits of $250,000 or more generally have stronger market opportunities, although smaller policies may qualify.
Future premiums: Buyers must consider how much they will spend maintaining the policy after purchasing it. Higher premiums can reduce the amount they are willing to offer.
Policy type: Universal life, whole life, and certain convertible term life insurance policies may qualify for settlement offers.
These considerations apply throughout the life settlement industry, not just to Coventry Direct.
However, different institutional buyers can evaluate the same information and arrive at different purchase prices.
Does Coventry Direct Pay More Than Other Life Settlement Companies?
There is no reliable way to conclude that Coventry Direct consistently pays more or less than any other life settlement company. Coventry Direct is the largest buyer in the marketplace, and purchases the most policies, but this does not necessarily mean they pay more.
The purchase price depends on the individual policy and the institutional buyers interested in acquiring it.
For example, one buyer might place greater value on a policy with relatively low annual premiums. Another may have different underwriting assumptions or investment requirements that make the same policy more attractive.
This is why two companies can review identical policy information and produce different offers.
Consider a hypothetical $500,000 life insurance policy.
One institutional buyer might offer $90,000, while another offers $115,000.
The difference is $25,000, even though both companies are evaluating the same coverage.
These figures are illustrative, not actual Coventry Direct offers.
The important point is that a policy’s value is not established by the first company willing to purchase it.
The strongest available offer is discovered by allowing qualified institutional buyers to compete for the policy.
That distinction matters when deciding how to approach the life settlement market.
Should You Contact Coventry Direct or a Life Settlement Broker?
Many seniors begin their research by contacting a company they recognize. Coventry, for example, is well established, well marketed, and very visible as a life settlement company. There is a good chance if you are reading this, you have already visited Coventry Direct’s website. Just searching “can I sell my life insurance policy” or “life settlement” will most likely populate with Coventry Direct at the top.
There is nothing inherently wrong with requesting information from an established life settlement company like Coventry. However, sellers should understand whether they are dealing with a direct purchaser, a broker, or a company that introduces policyholders to other market participants.
A direct purchaser evaluates a policy according to its own investment requirements. Coventry Direct falls into this category.
An independent life settlement broker represents the policyholder and seeks competing offers from institutional buyers.
These are different business relationships.
When a broker represents the seller, the objective is to obtain the strongest available purchase price through competition.
For example, Life Policy Solutions, a nationally recognized life settlement broker in California, works with institutional buyers throughout the life settlement market, including Coventry.
Rather than limiting the evaluation to one purchasing company, Life Policy Solutions presents qualifying policies to multiple buyers and negotiates competing offers.
This approach gives sellers an opportunity to determine whether another buyer places greater value on their coverage.
The difference can be significant, particularly for policies with larger death benefits.
What If You Already Have an Offer From Coventry Direct?
Receiving an offer from Coventry Direct or another life settlement company is an encouraging indication that your policy may have market value.
But before accepting, consider whether the policy has been exposed to competing institutional buyers.
A purchase offer reflects what a particular buyer is prepared to pay under the proposed terms.
It does not automatically establish the highest price available.
A seller who has already received an offer can ask an independent life settlement broker to evaluate whether additional institutional interest might produce a better result.
Life Policy Solutions provides this free look service without an upfront fee. They can review the policy and existing offer, determine whether additional buyers may be interested, and pursue competitive bids when appropriate.
There is no guarantee that another buyer will offer more. Some policies attract limited interest, and occasionally an existing offer may already be highly competitive.
Nevertheless, comparing available opportunities before accepting a substantial financial transaction can be worthwhile.
For seniors who have maintained life insurance coverage for decades, even a relatively small improvement in the settlement percentage can represent thousands of additional dollars.
Why Competition Matters More Than the Name of the Buyer
One of the most misunderstood aspects of life settlements is the importance of the purchasing company’s name.
Seniors frequently search for the best life settlement companies, the highest-paying buyers, and the most trusted companies purchasing life insurance policies.
These are reasonable questions.
But an established company’s reputation does not necessarily determine how much it will offer for a particular policy.
Institutional buyers make purchasing decisions based on their financial objectives and underwriting assumptions.
A buyer that submits the strongest offer for one policy may not submit the strongest offer for another.
This is why independent brokerage representation can be valuable.
Life Policy Solutions has spent more than 25 years negotiating life settlements on behalf of policyholders.
In one transaction, two institutional buyers submitted 22 competing bids for the same policy.
The competing buyers continued increasing their offers as negotiations progressed.
That experience demonstrates something important about the life settlement market: an initial valuation can change when buyers are competing for the same coverage.
Not every policy generates that level of interest, but the opportunity for competition is one of the principal advantages of independent brokerage representation.
How Much of the Settlement Does the Seller Actually Receive?
The purchase price is important, but sellers should also understand the amount they will receive after applicable commissions.
Some life settlement transactions involve brokerage fees that are deducted from the gross purchase price.
Life Policy Solutions caps its brokerage commission at 10% of the gross offer amount, with commissions averaging approximately 8%.
For example, if an institutional buyer agrees to purchase a policy for $150,000 and the brokerage commission is 8%, the seller would receive $138,000.
The purchasing buyer or provider handles the transaction’s closing arrangements, including applicable escrow procedures.
Before completing any life settlement, sellers should receive a clear explanation of the gross purchase price, applicable commissions, and expected net proceeds.
Understanding these figures makes it easier to compare and accept a competing offer.
Is Coventry Direct a Good Company to Sell Your Life Insurance To?
Coventry is the oldest and the largest participant in the life settlement industry, and they provide an excellent potential purchasing opportunity for eligible policyholders.
However, the better question for a seller may be whether Coventry Direct’s offer is the strongest available for their particular policy.
There is no single institutional buyer that consistently offers the highest price for every type of life insurance policy.
Different buyers have different purchasing requirements, and those requirements change over time.
For that reason, selecting a company based exclusively on brand recognition may not produce the best financial outcome.
An independent life settlement broker can help determine which institutional buyers are interested in a policy and whether competition can improve the purchase price.
How Life Policy Solutions Helps Seniors Compare Offers
Life Policy Solutions is an independent life settlement broker representing policyholders throughout the United States.
With more than 25 years of experience and hundreds of completed settlements, the company helps seniors evaluate their life insurance policies and obtain competitive offers from institutional buyers.
Unlike a company purchasing policies for its own investment portfolio, Life Policy Solutions represents the seller throughout the transaction.
Qualifying policies are presented to institutional buyers, offers are negotiated, and the seller receives a clear explanation of the available options.
Life Policy Solutions maintains an A+ Better Business Bureau rating, charges no upfront fees, and caps its brokerage commission at 10%.
Sellers are never obligated to accept an offer.
Whether you are considering contacting Coventry Direct, have already received an offer, or are beginning to explore selling your life insurance, Life Policy Solutions can help you understand what your coverage may be worth in the competitive market.
Visit cashoutlifeinsurance.com or call 1-844-440-7355 for a confidential, no-obligation evaluation.
The most important question isn’t simply how much one company will pay for your life insurance policy.
It’s how much the market is willing to pay when qualified buyers have an opportunity to compete.
People Also Ask
How much does Coventry Direct pay for life insurance policies?
Coventry Direct does not offer a fixed percentage of a policy’s death benefit. The amount depends on the insured person’s age, health, policy type, death benefit, and future premiums.
Can another life settlement company pay more than Coventry Direct?
Yes. Different institutional buyers use their own underwriting standards and investment criteria, which can produce different offers for the same life insurance policy. An independent life settlement broker can introduce competition among buyers and negotiate for a higher purchase price, although an improved offer is not guaranteed.
What percentage of a life insurance policy can you sell for?
Life settlement offers can range from approximately 5% to 60% or even more of a policy’s death benefit, depending on individual circumstances. Offers near the upper end are exceptional rather than typical. The actual value depends on the policy and the buyers interested in purchasing it.
Should I accept my first life settlement offer?
Before accepting an initial offer, consider having your policy evaluated by multiple institutional buyers. A first offer may be competitive, but it does not necessarily represent the highest available purchase price. Comparing offers also allows you to review brokerage commissions and understand your expected net proceeds.
Why use Life Policy Solutions instead of going directly to Coventry Direct?
Life Policy Solutions is an independent life settlement broker that represents the policyholder, not the purchasing buyer. Rather than relying on a single company’s valuation, Life Policy Solutions seeks competing offers from institutional buyers, including Coventry when appropriate. With more than 25 years of experience, no upfront fees, and brokerage commissions capped at 10%, Life Policy Solutions helps sellers pursue the strongest available offer for their coverage.
Can Life Policy Solutions help if I already received an offer from Coventry Direct?
Yes. Life Policy Solutions can review an existing Coventry Direct offer and evaluate whether other institutional buyers may be willing to pay more. There is no upfront fee or obligation to sell. Sellers can compare the available offers before deciding whether to proceed. Visit cashoutlifeinsurance.com or call 1-844-440-7355 to request an evaluation.