Understanding your agreement, financial offer, and who represents your interests can make a significant difference when selling your life insurance policy.
Selling a life insurance policy can provide meaningful financial value, particularly for seniors who no longer need their coverage or find the premiums difficult to maintain. However, receiving an offer is only part of the process. Before signing a life settlement contract, it is important to understand what you are agreeing to, how much money you will receive, and what happens to your policy after the sale.
One consideration deserves particular attention: whether your offer has been tested against other buyers. A life settlement contract may establish the terms of your sale, but it does not necessarily establish whether you received the highest possible price.
Key Takeaways
- A life settlement contract establishes the terms under which a life insurance policy is sold to a third-party buyer.
- Sellers should understand the purchase price, brokerage fees, payment arrangements, and ownership transfer before signing.
- The purchasing buyer or provider handles the closing and escrow arrangements.
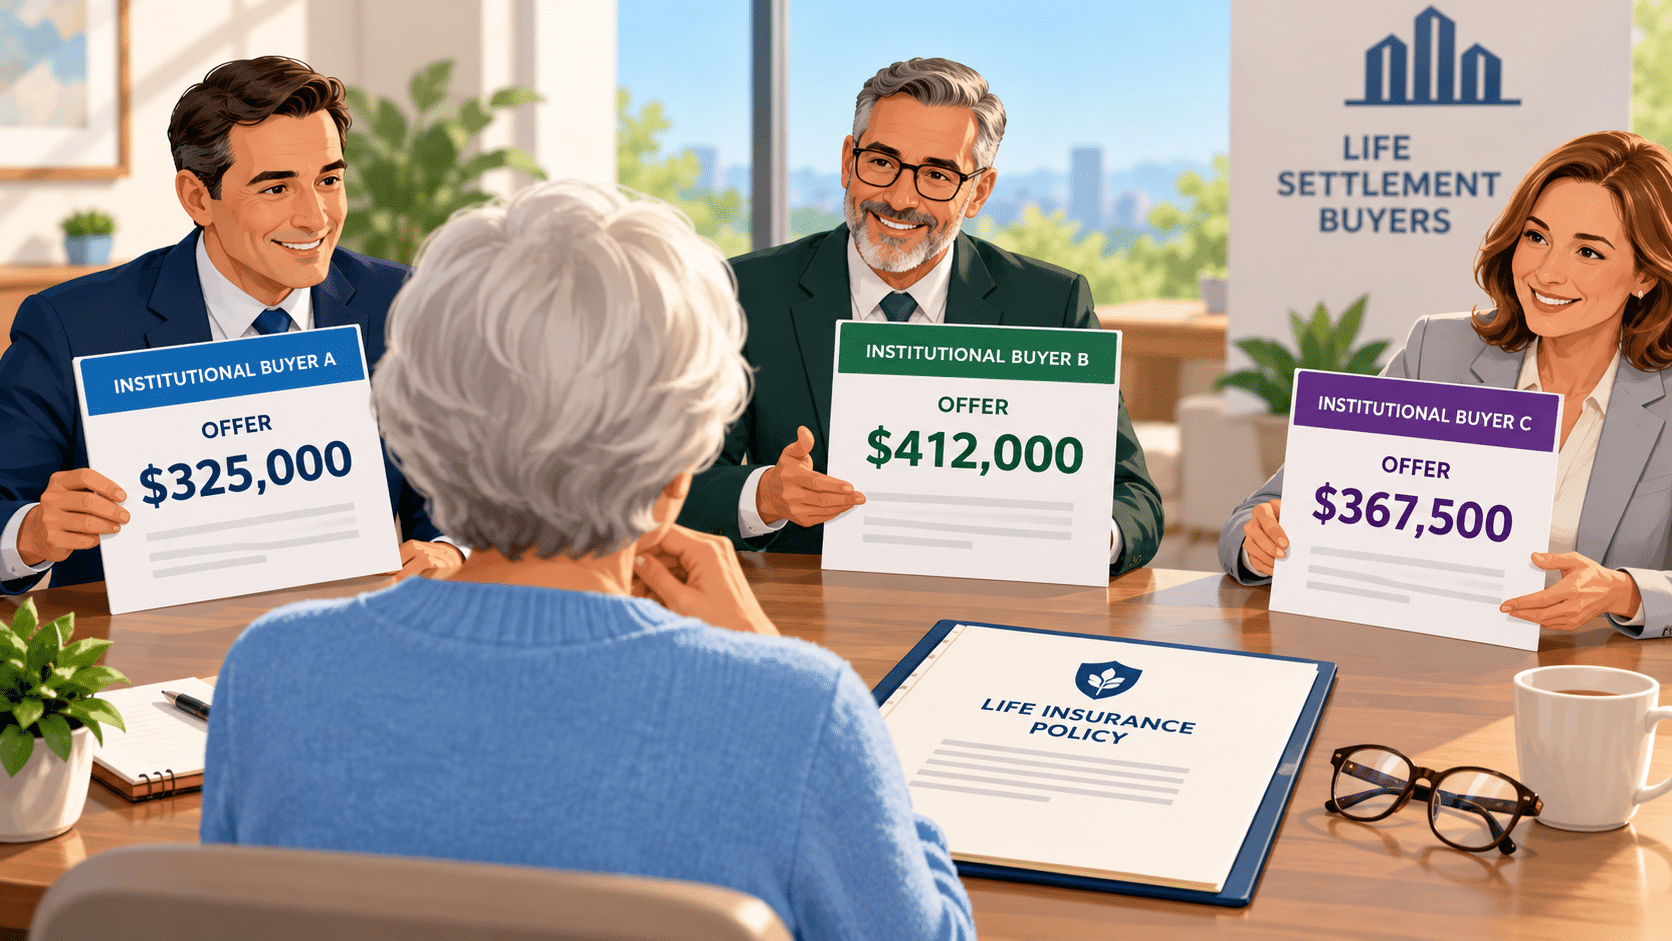
- Different buyers may offer different amounts for the same policy.
- An independent life settlement broker can represent the seller and negotiate competing offers before a contract is signed.
What Is a Life Settlement Contract?
A life settlement contract is a legal agreement between the owner of a life insurance policy and the company purchasing it. The agreement establishes the purchase price, conditions of the transaction, and requirements for transferring ownership.
Once the sale is completed, the purchasing buyer becomes the policy’s new owner and assumes responsibility for future premium payments. The buyer also becomes entitled to the death benefit when the insured passes away. In exchange, the seller receives an agreed-upon cash payment.
Unlike borrowing against a life insurance policy, a life settlement is an actual sale. The seller does not take on a repayment obligation, but the original beneficiaries generally give up their rights to the death benefit.
For qualifying seniors, this can provide access to money that would otherwise remain tied to the policy. Because the transaction permanently changes ownership, understanding the agreement is essential.
Understanding the Purchase Price and Your Net Proceeds
One of the most important details in a life settlement contract is the difference between the gross purchase offer and the amount the seller receives after applicable brokerage compensation.
For example, a buyer may offer $300,000 for a policy. If a broker is involved, the seller should understand how the commission affects the final proceeds before accepting the offer.
Life Policy Solutions provides complete transparency regarding the gross purchase price, applicable commission, and the amount the seller will receive. The company’s commission is capped at a maximum of 10% of the settlement amount, with no upfront costs or additional brokerage fees.
This distinction matters because the highest gross offer does not always produce the highest net proceeds. Sellers should evaluate the amount they will actually receive rather than focusing exclusively on the buyer’s initial offer.
Why Buyer Competition Matters Before Signing
A life settlement contract typically reflects the price negotiated between the seller and purchasing buyer. But how was that price determined, and could another buyer have offered more?
Life settlement buyers use different investment requirements, pricing assumptions, and portfolio strategies. One institution may value a particular policy differently from another based on the insured’s age, health, future premiums, or policy structure.
A seller who approaches a single direct buyer may receive only that company’s valuation. An independent life settlement broker can take a different approach by presenting the policy to multiple institutional buyers and negotiating competing offers.
Life Policy Solutions represents policyowners rather than purchasing policies for its own investment portfolio. Its objective is to create competition among interested buyers and pursue the strongest possible offer for the seller.
Not every policy attracts multiple bids, and no broker can guarantee a particular purchase price. However, exposing a qualifying policy to the competitive market can provide a more complete understanding of its potential value.
Before signing a life settlement contract, sellers should know whether their offer has been tested against other buyers.
How Escrow and Payment Arrangements Work
The closing process is another important part of a life settlement transaction. Sellers should understand how the purchase funds will be handled, when payment will be released, and what must occur before ownership transfers.
The purchasing buyer or life settlement provider coordinates the closing documents and applicable escrow arrangements. Escrow helps facilitate the exchange of payment and ownership according to the terms of the agreement.
Life Policy Solutions assists sellers throughout the closing process, helping them understand the required documentation and transaction steps. However, the purchasing buyer or provider is responsible for arranging escrow and coordinating the closing.
The objective is a clearly documented transaction in which the agreed-upon payment and policy transfer are completed according to the contract.
What Happens to Your Policy After the Sale?
Selling a life insurance policy changes its ownership and the financial rights associated with it. Once the transaction is completed, the purchasing buyer becomes responsible for maintaining the coverage and paying future premiums.
The buyer also becomes entitled to the death benefit. This means the seller’s original beneficiaries generally will no longer receive those proceeds.
For some families, this is an important consideration. A policy may have been purchased decades earlier to protect children, provide income for a spouse, or pay off a mortgage. Over time, those financial needs may change as children become independent, mortgages are paid off, and retirement expenses become more important.
The decision is not simply whether the policy provides valuable protection. It is whether maintaining that protection serves the family better than receiving the policy’s potential settlement value today.
Life Policy Solutions encourages sellers to consider both sides of that decision before proceeding.
Important Contract Terms to Review
A life settlement contract should clearly identify the purchasing party, agreed purchase price, conditions for completing the transaction, and responsibilities of everyone involved.
Sellers should also understand whether additional documentation, verification calls, or information updates will be required. After a completed sale, the insured may still be asked to provide occasional health or contact information updates, depending on the agreement.
Cancellation and rescission provisions also deserve attention. Applicable rights and deadlines can vary by state, so sellers should review their specific contract rather than assume every agreement provides identical protections.
If something is unclear, it should be explained before the documents are signed. Sellers may also wish to consult an attorney or tax professional regarding the legal and financial consequences of their particular transaction.
A well-understood contract allows the seller to proceed with greater confidence.
Who Represents Your Interests?
In a life settlement transaction, the seller and purchasing buyer have different financial objectives. The buyer is acquiring an investment and generally wants to purchase the policy at a favorable price. The seller wants to receive the highest possible amount.
A life settlement broker representing the policyowner works to obtain competitive offers and negotiate favorable terms on the seller’s behalf.
Life Policy Solutions operates exclusively as a life settlement broker, not a direct purchaser of policies. With more than 25 years of industry experience, the company works with institutional buyers to identify opportunities for competitive bidding.
Life Policy Solutions also provides free reviews of existing life settlement offers. This can be particularly valuable for someone who has already received an offer from a direct buyer but has not yet signed a binding agreement.
An existing offer does not necessarily represent the highest price available in the market. Understanding that distinction before signing can make a meaningful financial difference.
Know What Your Policy Is Worth Before Signing
A life settlement contract is an important financial agreement, but the process should begin well before the paperwork arrives. The first step is understanding whether the policy qualifies for a settlement and what buyers may be willing to pay.
Age, health, policy size, and future premium obligations all influence buyer interest. In today’s market, seniors age 75 and older with policies of $250,000 or more often represent stronger candidates, particularly when health has declined. Other situations may also qualify.
Life Policy Solutions evaluates each policy individually and helps sellers understand whether a competitive market exists.
The company’s free Life Settlement Calculator provides a starting point for exploring potential value. However, a calculator estimate is not a purchase offer. Actual value depends on buyer evaluation and market interest.
For sellers who already have an offer, Life Policy Solutions can review the proposal and determine whether additional buyer competition may improve the result. There is no upfront cost and no obligation to accept an offer.
The most important decision may not be whether to sign a life settlement contract. It may be whether you have received the best available offer before signing.
Frequently Asked Questions
What is a life settlement contract?
A life settlement contract is a legal agreement establishing the terms under which a life insurance policy is sold to a third-party buyer. It identifies the purchase price, transfer requirements, and responsibilities of the parties involved.
Who prepares the life settlement contract?
The purchasing buyer or life settlement provider typically prepares the transaction documents and coordinates closing arrangements. A broker representing the seller helps explain the documents and assists throughout the process.
Who does a life settlement broker represent?
A life settlement broker acting on behalf of the policyowner represents the seller’s interests. Life Policy Solutions works for the seller rather than purchasing policies for its own investment portfolio.
Can I negotiate a life settlement offer before signing?
Yes. Life settlement offers can be negotiated, and competing buyers may offer different amounts for the same policy. A broker can seek additional offers and use competition to negotiate more favorable terms.
What happens to my beneficiaries after a life settlement?
After ownership and beneficiary rights are transferred, the purchasing buyer generally becomes entitled to the death benefit. The seller’s original beneficiaries no longer receive those proceeds.
Can I cancel a life settlement contract after signing?
Cancellation or rescission rights depend on applicable state law and the contract terms. Sellers should review these provisions carefully before signing and seek legal guidance when necessary.
Should I get a second opinion before accepting a life settlement offer?
A second opinion can be valuable, particularly when an offer comes from a single direct buyer. Life Policy Solutions offers free reviews of existing offers to determine whether additional competition could produce a better result.